| The First Art Newspaper on the Net | Established in 1996 | Portugal | Tuesday, March 7, 2017 |
|\| ART BLOG HUMOR BLOG PHOTO BLOG CULTURE BLOG |:| FOR THE RENAISSANCE MAN & THE POLYMATH WOMAN |/|
Tuesday, March 7, 2017
Portugal formally scraps sale of its Miro collection
Exhibition at Museu Nacional de Arte Antiga aims to reconstitute the heart of Lisbon during the Renaissance
| The First Art Newspaper on the Net | Established in 1996 | Portugal | Tuesday, March 7, 2017 |
Is Art an Object of Passion or an Asset Like Any Other?
ARTSY EDITORIAL
BY ANNA LOUIE SUSSMAN
MAR 3RD, 2017 7:12 PM
As the global ultra-rich snap up trophy artworks and build collections scattered around many homes and storage facilities, art services are becoming an increasingly important part of wealth professionals’ offering to help these collectors manage their financial lives.
A Thursday panel at Deloitte’s U.S. Art & Finance Conference at The Armory Show featured five art and finance professionals discussing the evolving relationship between art and financial services.
It launched with Philip Hoffman, founder and CEO of The Fine Art Group, harking back 18 years to when he was planning the launch of his art investment fund, The Fine Art Fund. Hoffman recalled how at the time, “everyone said it was very crude” to approach art as an asset class, since “art was about passion.” Fast-forward 18 years and now everyone’s doing it, he said, ticking off the names of banks with art services departments.
How did that point of view evolve? One reason is the sheer scale of the value of artworks today. Art transactions have recently accounted for over $60 billion annually. That doesn’t mean all or even most collectors go in with an investment mindset—everyone on the panel stressed that collecting begins with a passion for art. But, said Henry Johnson, vice chairman for the East Region at Northern Trust Wealth Management, sometimes a collection “grows to such a size that you can’t ignore it.” For Johnson, that threshold is roughly 20% of a family’s or individual’s net worth, rather than an absolute number. For example, he’s met families with $50 million art collections who aren’t even thinking about it as an asset.
Leon Bailey, chief financial officer at the Duncan Family Office, said that while his clients collect art on a very personal level, they have over 900 artworks, enough to make the collection account for a serious portion of their wealth. Part of his role is to help track, maintain, and insure the works.
Evan Beard of U.S. Trust/Bank of America Private Wealth Management said his own bank has seen its art lending portfolio grow from $1 billion to $6 billion. One of the key enablers of growth in art-related financial services was the increased comfort and interest on the part of his colleagues in the underwriting and risk-management teams, thanks to the growth and depth of the auction markets.
Beard needled fellow panelist Brook Hazelton, president of Christie’s in the Americas, for offering in-house advisory services to clients that he said are inevitably biased towards a sale. But he said he was grateful for the service auction houses provide: creating a publicly available data set the bank and others can use to understand prices and underwrite loans. In a separate conversation with Artsy, he contrasted today’s environment, with its vast online repositories of pricing data, with the 1980s, when looking up data meant dusting off a bunch of old binders at Sotheby’s.
He described art and other tangible assets such as cars and yachts as the last frontier for clients who have financialized nearly every other aspect of their lives, throwing out an estimate of $1 trillion in tangible assets that every bank is keen to help lend against. “That’s a nut we’re all trying to crack,” he said.
What do these already wealthy people do with their art-secured loans? Beard said he’s seen his clients use the capital raised against their art (typically done at a 50% loan-to-value ratio) to buy more art, to scale up their philanthropy, or to reinvest in their existing businesses. He mentioned a real estate developer who leveraged his art to build cancer centers that will house the collection, a woman who used her art collection to raise the cash to sue her husband in the middle of divorce, and another developer who built enough hotel rooms in his city to host the Super Bowl.
“People are now using it as an internal source of liquidity,” he said. The bank, he said, sees art more as a capital asset than an investable asset, meaning they feel comfortable lending against it, but wouldn’t invest in it with the intention of profiting off a later resale.
Of course, art prices do go up, and that’s another reason art specialists have a role to play in broader wealth management. Johnson described an increasingly common estate planning scenario, in which parents bequeath art to their children based on sentimental attachment. He told one story of a couple who bought two paintings for $500,000 each in the 1970s. They left one, a Frank Stella painting, to one son who went on to become a teacher. The other, Clyfford Still painting, went to the other son, who went on to become a private equity titan. But the Stella is now worth $10 million, while the Still is worth $45 million. He said estate planning that includes specialized art knowledge can help foresee and plan for such eventualities, so as to avoid conflict within the family later on.
That also raised the question of value. Hoffman asked how people could feel comfortable wading into a market where two similar-looking paintings can fetch prices hundreds of thousands of dollars apart. Even if they get a discount, what are they to make of the initially quoted price? How can they move past the information asymmetry, or the conflicts of interest posed by art advisors or dealers who are motivated to make a sale at all cost?
Part of the answer is trusting your gut, said keynote speaker Anne Dias Griffin, in her opening address. In many ways, amassing an art collection requires the same skills as those of a successful investor. Griffin, founder and managing partner of Aragon Global Management, and a former investor under George Soros, is a prominent Chicago-based collector formerly married to hedge fund billionaire Ken Griffin. Both collecting and investing reward pattern recognition, the ability to carefully assess value, and due diligence, but they diverge in one respect: Art collecting is “a really personal endeavor,” she said. A collection “grows into a form of self-portrait.”
“Take risks, make bets,” she said. “If you’ve trained your eye, you will know when it’s right to go for it.”
—Anna Louie Sussman
The Market Is Changing What Art Looks Like
ARTSY EDITORIAL
BY ISAAC KAPLAN
MAR 4TH, 2017 8:00 PM
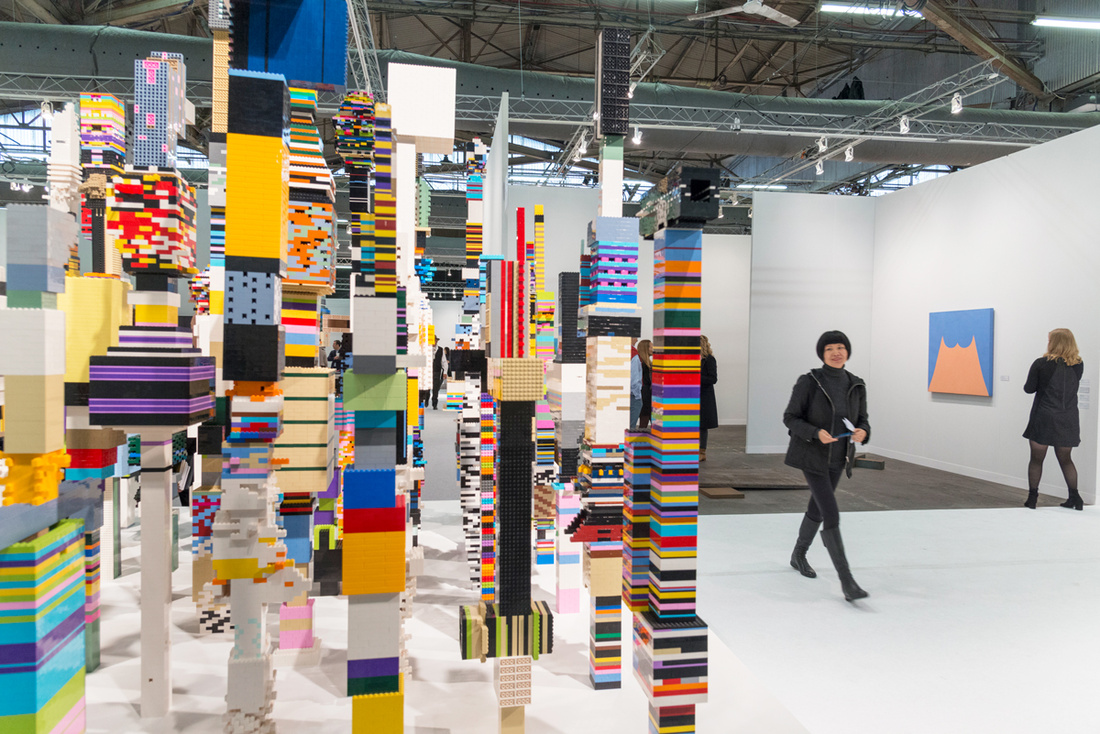
Installation view of Douglas Coupland, Towers, 2014, at The Armory Show, 2017. Photo by Adam Reich for Artsy.
On Friday at The Armory Show, a panel of art insiders gave their thoughts on the future of the market to a packed house. Moderator Kelly Crow of the Wall Street Journal was joined by auctioneer Simon de Pury, art advisor Todd Levin, collector Alain Servais, CEO of Athena Art Finance Andrea Danese, and gallerist Dominique Lévy of Lévy Gorvy.
Crow opened the discussion by prompting the audience members to do the near-impossible: truly use their imaginations.
“Close your eyes and try to conjure a color that you have never seen before,” said Crow, admitting that when asked to do the same thing she failed—only familiar colors came to mind. That reflex is “an apt metaphor for trying to understand the art market,” she said, before diving into a conversation that at times tried to conjure the future, but largely consisted of parsing more familiar recent market trends. That’s not to say there weren’t valiant attempts at prognostication, up to and including the use of props: A smiling Levin at one point pulled out a Magic 8-Ball when asked how he decides if a work of art is a good purchase.
Don’t Expect Data to Tell You What to Do
The art market will never behave the way some investors perhaps yearn for it to behave—that is, as a normal commodity market. “The bottom line is that art is a qualitative object,” Levin said. “Not a quantitative set of data points.” The art world, never one for rapid change and disruption, is nevertheless starting to integrate quantitative data, a primary example being online databases of auction prices. As more information becomes available online, buyers are seeking to complement their subjective taste with quantitative assessments. But available sales data is inherently limited and spotty, particularly for emerging artists with a minimal or nonexistent track record.
Even for more established artists, each work is different, Levin said. If a work has been damaged, or has been burned at auction before, there will always be a role for connoisseurship, knowledge, and personal experience when assessing a purchase. But De Pury acknowledged the desire, even for those who buy a work out of love, to not want to “throw this money out the window,” as he put it. “You feel vindicated if your passion translates into a good investment as well.”
Big Money is Changing the Market
Though the art market is still comparatively miniscule compared to other sectors of the economy (in 2016, it was roughly equal, in total value, to how much Americans spend on pet food, Servais said), it has expanded rapidly in recent years. Servais mentioned the fact that, in 2001, contemporary artists (those born after 1960) at auction netted $48 million annually. In 2007, that figure was $800 million. The size of the market “changed, completely, the rules of the game,” he said. “This is also what brought the finance guys,” Servais continued, putting it on the radar of those looking to financialize art—something he said is a major mistake.
Danese said the amount of wealth pouring into the market may push it to be a more efficient, data-driven area of commerce. Those investors—many of whom come from finance—will want clear information in order to make informed decisions, as they might with stocks or other investments. “There will have to be a dramatic change,” he said. Levin said this was also a function of macroeconomic factors, such as low interest rates, which were intended to jumpstart the economy. One effect they’ve had is to allow vast amounts of money to end up in the hands of a relatively small group of people, often the same people who buy art. “That money has to go somewhere,” Levin said.
RELATED ARTICLE

Is Art an Object of Passion or an Asset Like Any Other?
The Market is Changing What Art Looks Like
A 2016 Deloitte finance report found that 72% of collectors “bought art for passion with an investment view.” And there is no doubt money is impacting, not just the market, but art itself. Servais said that New York is “probably” the “sickest city in terms of the influence of money at all levels of the arts...It even goes to the level of the artist. Because the artists are producing what the market wants.” Take the advent of Zombie Formalism, when artists were pumping out hundreds of monotonous abstract works to meet the demand of speculators. Broadly, the tastes of new collectors without experience, even if they’re not speculators, tend to gravitate towards picking up art that isn’t too challenging, incentivizing artists to produce work for consumption and not for its artistic value.
For her part, LĂ©vy critiqued treating art purely as a question of dollars and cents. “We’re talking about a market, and we’re forgetting we’re talking about art,” she said, adding that to chalk the growth of art simply to more and more money “actually makes me angry.” Challenging the idea that market factors are primarily responsible for a booming interest in art, LĂ©vy instead cited an increasing number of interested collectors, a more globalized world, people venturing out of their cultural niches, and artists entering the digital space as the key factors driving the market. Focusing purely on the monetary and not on the intangible aspects of collecting and the creativity of artists is the “exact thing I would like to see changing,” she said. And despite the emphasis on making savvy financial plays in how one purchases art, she’s seen people buying spontaneously and emotionally.
Though the future is murky, one thing is certain: Even though the art market is comparatively small, there is room to grow. Though some have put excess cash in art, Danese noted only 4% of ultra-high-net-worth individuals are buying or collecting art. “You have a huge opportunity out there, Dominique,” he said, smiling in the direction of the gallerist.
—Isaac Kaplan
Subscribe to:
Posts (Atom)