— One big beneficiary of the Trump administration’s efforts to dismantle the Affordable Care Act: insurance that barely covers anything. Dozens of customers of one such insurer say they were tricked into buying plans that left them stuck with surprise bills. (Bloomberg Businessweek)
Health Insurance That Doesn’t Cover the Bills Has Flooded the Market Under Trump
The administration’s moves to weaken the Affordable Care Act have taken hold, and companies are cashing in.
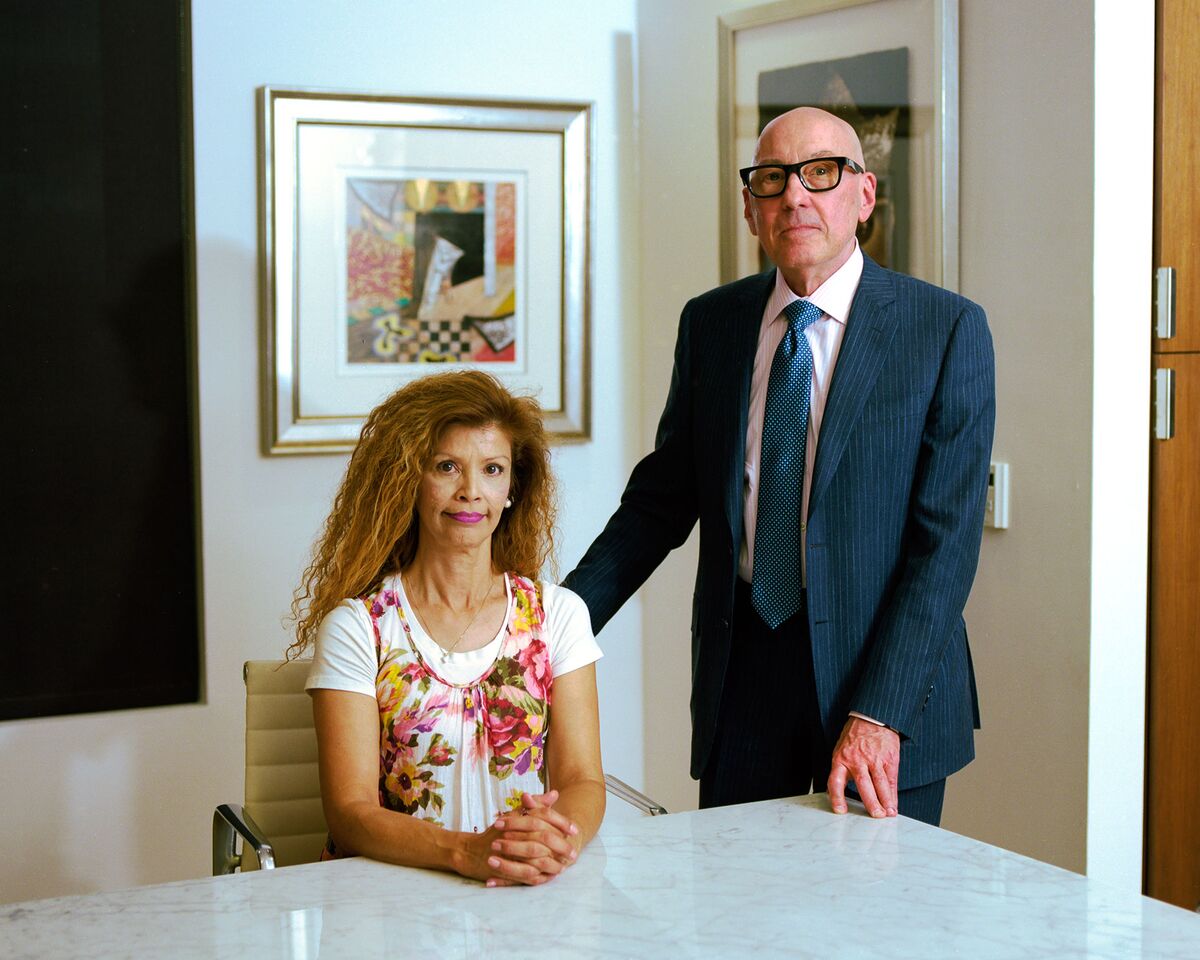
Marisia Diaz and her lawyer Charles Surrano.
PHOTOGRAPHER: CASSIDY ARAIZA FOR BLOOMBERG BUSINESSWEEK
By
Zeke Faux
,
Polly Mosendz
, and
John Tozzi
Early one Friday morning two years ago, David Diaz woke up his wife, Marisia, and told her he didn’t feel right. He asked her to pray with him. Their son called 911, and within minutes, Marisia was tailing an ambulance down the dirt road away from the couple’s house on the outskirts of Phoenix to a hospital in the city. David had had a massive heart attack.
Before being wheeled into surgery, he whispered the PIN for his bank card to Marisia, just in case. But the double-bypass operation was successful, and two weeks later he was discharged.
On her way out, Marisia gave the billing clerk David’s health insurance card. It looked like any other, listing a copay of $30 for doctor visits and $50 for “wellness.” She’d bought the plan a year earlier from a company called Health Insurance Innovations Inc., with the understanding that it would be comprehensive. She hadn’t noticed a phrase near the top of the card, though: “Short-Term Medical Insurance.”
The Diazes’ plan was nothing like the ones consumers have come to expect under the 2010 Affordable Care Act, which bars insurers from capping coverage, canceling it retroactively, or turning away people with preexisting conditions. But the law includes an exemption for short-term plans that serve as a stopgap for people between jobs. The Trump administration, thwarted in its attempts to overturn the ACA, has widened that loophole by stretching the definition of “short-term” from three months to a year, with the option of renewing for as long as three years.
Fewer than 100,000 people had such plans at the end of last year, according to state insurance regulators, but the Trump administration says that number will jump by 600,000 in 2019 as a result of the changes. Some brokers are taking advantage, selling plans so skimpy that they offer no meaningful coverage. And Health Insurance Innovations is at the center of the market. In interviews, lawsuits, and complaints to regulators, dozens of its customers say they were tricked into buying plans they didn’t realize were substandard until they were stuck with surprise bills. The company denies responsibility for any such incidents, saying it’s a technology platform that helps people find affordable policies through reputable agents.
Six months after David’s surgery, the Diaz family got a particularly big surprise bill—an error, Marisia thought when she saw the invoice. But when she called her insurer, she was told she’d have to pay the full amount: $244,447.91.
Diaz
PHOTOGRAPHER: CASSIDY ARAIZA FOR BLOOMBERG BUSINESSWEEK
The ACA was designed around a fundamental economic bargain: Insurance companies would no longer be allowed to deny coverage to people who were already sick, and policies would have to cover a broad set of benefits, including prescription drugs, maternity care, and hospitalization. In return insurers were guaranteed that consumers would buy coverage or face tax penalties, and that subsidies would be available for people who needed them. The approach spread the financial risk of getting sick and aimed to guarantee that no one with insurance would have to worry about being bankrupted by necessary care. Preserving the bargain was essential, though; too many exceptions, and the edifice would crumble.
When the Republican-controlled Senate failed in 2017 to pass Trump-backed legislation that would have gutted the ACA, the administration instead seized on the loophole allowing consumers to buy certain noncompliant plans. Trump used an executive order to extend the time limit for temporary plans, which he and other Republicans talked up as a potential solution for cash-strapped consumers. Healthy people, they argued, could save money by buying policies that didn’t cover perceived nonessentials. “These plans aren’t for everyone, but they can provide a much more affordable option for millions of the forgotten men and women left out by the current system,” Health and Human Services Secretary Alex Azar said in August 2018.
By then, the ACA system was already wobbling. Aetna Inc. and some other big insurers had been dropping off the state exchanges created for consumers to buy compliant plans, leaving a void that “junk insurers,” as critics tagged them, rushed to fill. A recent study by Sabrina Corlette, a research professor at Georgetown University’s Health Policy Institute, showed that ads for such plans often appeared at the top of internet searches for the government-run marketplaces. Health insurance also became the most common product pitched in robocalls—responsible, according to call-blocking service YouMail, for 387 million calls this April alone.
One company that moved nimbly to capitalize on the uncertainty was Health Insurance Innovations, known by its stock ticker, HIIQ. Founded in Tampa in 2008 by Michael Kosloske, whose father and grandfather both ran health insurance brokerages, the company sought to provide a clearinghouse for brokers who sold cheap insurance to individuals. It worked with insurers to devise a menu of plans, designed software for the brokers, and ran a call center to handle customer service.
After the ACA passed in March 2010, HIIQ continued promoting short-term plans and other limited forms of insurance that didn’t have to comply with the new rules for comprehensive plans. In an interview with Fox News a few years later, Kosloske argued that these policies offered the same benefits at half the cost. “There’s challenges with the Affordable Care Act, and we think our products provide a solution,” he said.
The pitch worked, and Kosloske’s company became one of the biggest players in its niche. When Trump took office, investors saw potential for expansion. HIIQ’s shares tripled within two years of his inauguration, making Kosloske’s stake worth more than $150 million at its September 2018 peak; he lives in one of Tampa’s swankiest mansions and flies around in a Dassault Falcon 2000 jet. The company has also paid its chief executive officer since 2016, Gavin Southwell, at least $14 million in the role. HIIQ now brings in more than $350 million in revenue annually, and it projects that this year will be its most profitable yet.
Marisia Diaz found HIIQ when she was forced to go online to shop for insurance in 2016. In many respects, she and her husband were just the kind of people the Trump administration argues Obamacare has left behind. Most mornings, Marisia, an orange-haired 56-year-old who’s a little over 5 feet tall, would wake before dawn to read the Bible and tend her chickens. She’d quit her job at a local utility to take care of her grandchildren and started spending her days chasing them around the lemon, peach, and tangelo trees outside the family’s modest ranch house. David, a 49-year-old home remodeling contractor, made a decent living but didn’t get health insurance through his employer.
For years, the Diazes had paid for comprehensive coverage from Aetna, but the insurer had recently announced it would no longer offer ACA plans in more than two-thirds of the U.S. counties it served, including the couple’s, citing cost-control concerns. Eager to avoid the ACA marketplace, which she’d heard negative stories about, Marisia turned to Google to find a provider. She wrote down a slew of toll-free numbers and called them all, taking notes about their offerings.
Her first call was to HIIQ. She reached a broker named Linda Thiel, who was working from an office on Friendly Lane in Haltom City, Texas, for a subsidiary of HIIQ called American Service Insurance Agency LLC. “She was very friendly, seemed like she cared, and seemed like she wanted to give us the best plan for our family,” Diaz recalls. “I trusted that.”
After hearing out other brokers, she returned to Thiel. Diaz says Thiel led her to believe that the plan she wanted to buy, LifeShield STM, was similar to her old one, even though it cost only about $400 a month, less than her Aetna coverage. Had Diaz gone to the ACA marketplace, the family would have qualified for subsidies, but Thiel didn’t mention that, Diaz says. She recalls the broker saying the policy had an impressive coverage limit of “three-quarters of a million dollars” after a maximum $7,500 deductible. Thiel acknowledged that some things wouldn’t be covered, like prenatal care and addiction treatment, but, Diaz says, the rest of the disclaimer went by so quickly she couldn’t follow the details.
By the time of David’s heart attack, the LifeShield plan had expired, so Thiel had shifted the Diazes to a similar plan from Everest Reinsurance Co. The new one also had a $7,500 deductible, so Marisia got a credit card with a 0% introductory rate and, when David was discharged, had Banner-University Medical Center Phoenix bill that amount to the card.
She thought that would take care of their portion of the total, but it wasn’t long before bills started to arrive. The ambulance company wanted $1,171.50. An internist wanted $1,139 for a day’s care. When the billers requested David’s insurance information, Marisia provided it. “Sometimes it takes a while for a claim to be processed and paid,” she says. “I didn’t think too much of it.” Emergencies such as this were what insurance was for.
It wasn’t until February 2018 that she really began to take notice. One of the new letters was stamped “past due.” Another said “final notice.” Another said “delinquent,” highlighted in red. Still another was the “total you owe on all accounts”—the bill for $244,447.91, three times the value of the Diazes’ home.
When Marisia called Everest’s claims department, the representative was blunt: The insurer wouldn’t be paying anything beyond the $4,000 the plan had already covered. Marisia dialed Thiel and reminded the broker that the family’s plan was supposed to be comprehensive. She remembers Thiel contradicting herself on the call, at one point saying there must have been a mistake, perhaps with billing codes, then later saying Diaz had been told the family’s plan was very limited and wouldn’t cover such bills.
Marisia soon learned about the policy’s limitations. The Everest plan didn’t cover preexisting conditions, limited the number of doctor visits, and capped hospital coverage at $1,000 a day. It allowed a maximum of $250 per emergency room visit and $5,000 per surgery, not nearly enough to cover the usual cost of those services. Most benefits didn’t kick in until the $7,500 deductible was met. And the listed maximum total payout of $750,000 was misleading: It didn’t mean the Diazes’ bills would be covered up to that amount after they paid the deductible; it just meant that if Marisia underwent, say, 150 surgeries, she could get $5,000 for each, leaving her to cover millions of dollars in additional bills.
Once Marisia realized the bills for David’s heart attack wouldn’t be covered, she frantically called medical offices. As the couple discussed what to do, David started talking about bankruptcy. Marisia tried to put on a brave face. “Don’t talk that way,” she recalls telling him. “God is going to take care of us.” The couple didn’t tell their friends or family about their debt, except for their son, Mickey, who does communications for a law firm in Phoenix. He got them a referral for an attorney named Charles Surrano.
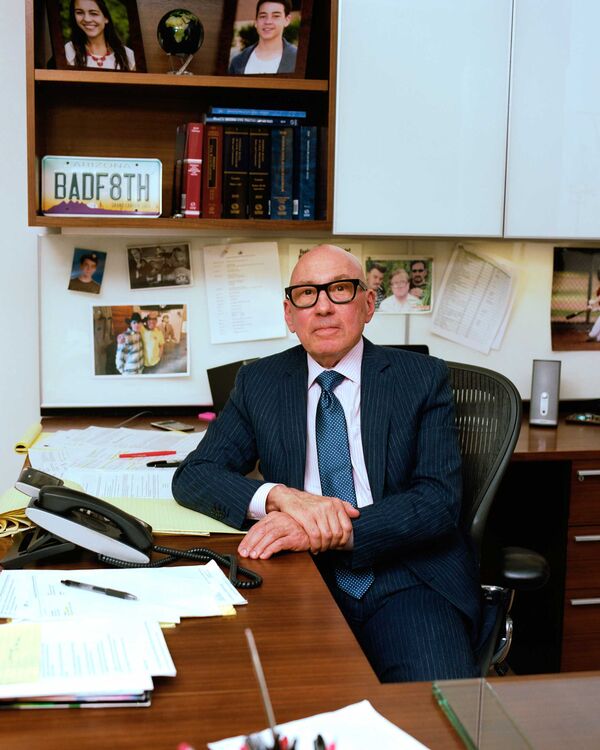
Surrano
PHOTOGRAPHER: CASSIDY ARAIZA FOR BLOOMBERG BUSINESSWEEK
Surrano once defended insurers. Now he sues them. He specializes in “bad faith” cases, in which companies deny claims without basis. He once won a $59 million judgment for a client whose disability insurance payments were stopped by an insurer that was systematically cutting off its most expensive customers. Originally a New Yorker, Surrano has worked in Arizona for more than 30 years. The conference room at his office overlooking downtown Scottsdale overflows with fake succulents, and his shelves display twin license plates reading GOODF8TH and BADF8TH. (The one on his Tesla says REASON.)
In August 2018, after meeting the Diazes and hearing their story, he filed a lawsuit against HIIQ, Everest, and Thiel, accusing the broker and HIIQ of consumer fraud and negligent misrepresentation, and Everest of breach of contract. Everest says in court filings that the Diazes were informed of the limitations of the policy and that it handled claims appropriately. HIIQ and Thiel denied the allegations but didn’t provide an alternative version of events. The company told Bloomberg Businessweek it couldn’t discuss the specifics of any particular customer’s experience but said in a statement that it requires brokers to disclose the limitations of any policies they sell. It also said it isn’t an insurer and isn’t responsible for coverage decisions made by insurers whose policies it offers.
Surrano saw insurers behaving badly long before Obamacare, but he credits the Trump administration with the abuses being perpetrated today. “Creating an exception to the requirements of Obamacare is what gave rise to this kind of stuff,” he says. “This is what you get—you get people like Mrs. Diaz and her family.”
Similar stories aren’t hard to find. Complaints to the Federal Trade Commission obtained by Businessweek via the Freedom of Information Act detail numerous cases of HIIQ customers buying medical insurance they believed was comprehensive, then having their claims rejected or barely paid out. “I feel me really dumb,” wrote one person who’d found out her ADHD medication wasn’t covered. Another customer said she was reminded of the John Grisham novel The Rainmaker, in which an insurance company has a policy of rejecting every claim. Trudy Slawson, a 65-year-old in Great Falls, Mont., who bought an HIIQ-administered plan in 2016, thought she had comprehensive coverage until getting a surprise bill for $60,000 after her husband’s emergency gallbladder removal. The insurer paid only $100. “I believed what they were telling me,” she says.
Some brokers who’ve worked with HIIQ have run into trouble with regulators. The Massachusetts attorney general is investigating HIIQ and at least one brokerage that formerly sold for the company over what she calls misleading tactics. “You sell bad products to people under false terms,” an anonymous reviewer on indeed.com wrote of the brokerage. “You get paid well if you scam enough people.”
HIIQ doesn’t directly employ brokers, but the company says it goes to great lengths to ensure that agents are honest with customers, including by providing training, running background checks, conducting site visits, and staging phone calls from secret shoppers. Those who break the rules can be kicked off the platform. “HIIQ has diligent vetting and effective ongoing compliance monitoring,” Elizabeth Locke, an attorney representing the company, wrote in a letter to Businessweek. Last year, HIIQ settled a 43-state investigation into broker sales practices by agreeing to pay $3 million and monitor salespeople more closely, without admitting wrongdoing.
A recent FTC lawsuit raised further questions about how closely the company has been watching its brokers. Filed in November 2018 in federal court in Fort Lauderdale, the suit sought to shut down a group of boiler rooms run by a flashy 35-year-old named Steven Dorfman. The FTC said he’d swindled tens of thousands of people out of more than $100 million by passing off “sham” insurance policies as comprehensive health insurance, spending the profits on private jet flights, a white Lamborghini Aventador, a black Rolls-Royce Wraith, and a $300,000 wedding in Bal Harbour, Fla. One former customer service manager told the commission that Dorfman’s operation fielded as many as 3,000 complaints a day.
The FTC said that Dorfman was selling policies through HIIQ and that the company had paid him $145.7 million in commissions across several years, meaning he might have been one of HIIQ’s biggest brokers. Dorfman, who declined to comment, denied the allegations. HIIQ, which wasn’t sued itself, said that it had stopped doing business with Dorfman as soon as the case was filed.
Hedge funds that bet against corporate wrongdoers took notice of the FTC’s lawsuit. Last year an anonymous short seller posting under the pen name Aurelius Value wrote a blog post calling attention to the company’s connection with Dorfman. “We believe it is now a question of when, not if, HIIQ’s business will implode,” he said. In May, HIIQ was the most shorted stock in the country, according to financial analytics company S3 Partners LLC.
Southwell, the CEO, told Wall Street analysts that his company was under attack. “It is certain people’s full-time job to try to attack this business with never-ending, false, and misleading information,” he said. “It is our day job to keep building a successful growth company with incredible cash flow.” He asserted that HIIQ’s regulatory problems were in the past, accused critics of cherry-picking unhappy customers, and singled out four happy ones whose costly medical problems had been covered entirely by policies bought through HIIQ.
“We are not perfect,” he said. “The health system here has major issues, which are well-publicized, and we work hard to keep improving, so we have less complaints and less issues than anyone else that we are aware of.” He also said it’s heartbreaking when a broker misleads a customer or an insurer denies a valid claim.
When customers have made accusations to that effect in court, the company has defended itself aggressively. Charley Butler, a truck driver in Montana, filed suit in April 2017 after his insurance didn’t pay for his testicular cancer treatment, leaving him with $69,000 in unpaid bills. During a deposition the following year, Lee Henning, an attorney for HIIQ, tried to undermine Butler’s claim that the debt had left him anxious. If you need money so badly, Henning asked, why doesn’t your wife get a second job? He reminded Butler that the Bible says a wife should be a good “helpmate.”
“I’m really sorry for everything you’ve gone through,” he said next. “But whether or not the insurance company had handled your case differently, you still would have had cancer, correct?” Henning didn’t respond to a request for comment; HIIQ says he no longer represents the company and that it doesn’t condone his comments to Butler.
On June 14, Trump held a ceremony in the White House Rose Garden to announce a new policy that lets employers steer as much as $1,800 in tax-exempt funds to their employees instead of offering them comprehensive health plans. The move will likely create many more customers for HIIQ’s industry. “We’re putting the people back in charge with more choice for better care at a far lower cost—and other people will not be paying for their health care,” Trump said.
Brokers are already gearing up for November, when the open enrollment period for Obamacare plans will drive millions of potential customers online. Earlier this year, HIIQ paid roughly $70 million to buy TogetherHealth, a company that runs TV ads targeted at over-65 shoppers and directs those who call in toward insurance brokers. Southwell told Wall Street analysts that TogetherHealth brings in a million customers a year, and that HIIQ can redirect them to its network of brokers and products. “There is much low-hanging fruit in the over-65 space,” he said. “We expect significant growth.” HIIQ has since announced that it’s conducting a strategic review, essentially putting itself up for sale to private equity firms, which would get it off the stock market and solve its problem with short sellers once and for all.
As for the Diazes, Surrano is looking to take depositions from Thiel and other HIIQ representatives, a process that could take months. It’s unlikely a trial would start before next summer. In the meantime, the couple is still struggling with the debt from David’s heart attack.
After the initial wave of bills came in, Marisia started sending $10 to each of their creditors, attaching a signed note asking the recipient to accept the money as a “payment of good faith.” The debt is never far from her mind. “I wake up thinking about it,” she says. “I go to bed thinking about it. It doesn’t go away.” The family switched to a comprehensive, ACA-compliant insurance policy in December 2017. With government subsidies, it costs less than they were paying for junk insurance. —With Tatiana Darie
Long before the term “influencer” was coined, young people played that social role by creating and interpreting trends. Now a new generation of influencers has come on the scene. Members of Gen Z—loosely, people born from 1995 to 2010— are true digital natives: from earliest youth, they have been exposed to the internet, to social networks, and to mobile systems. That context has produced a hypercognitive generation very comfortable with collecting and cross-referencing many sources of information and with integrating virtual and offline experiences.
As global connectivity soars, generational shifts could come to play a more important role in setting behavior than socioeconomic differences do. Young people have become a potent influence on people of all ages and incomes, as well as on the way those people consume and relate to brands. In Brazil, Gen Z already makes up 20 percent of the country’s population. McKinsey recently collaborated with Box1824, a research agency specializing in consumer trends, to conduct a survey investigating the behaviors of this new generation and its influence on consumption patterns in Brazil. 1 The survey coupled qualitative insights about Gen Z in three of the country’s major cities (Recife, Rio de Janeiro, and São Paulo) with multigenerational quantitative data that cut across socioeconomic classes. Our goal was to understand how this new generation’s views might affect the broader population, as well as consumption in general.
Our study based on the survey reveals four core Gen Z behaviors, all anchored in one element: this generation’s search for truth. Gen Zers value individual expression and avoid labels. They mobilize themselves for a variety of causes. They believe profoundly in the efficacy of dialogue to solve conflicts and improve the world. Finally, they make decisions and relate to institutions in a highly analytical and pragmatic way. That is why, for us, Gen Z is “True Gen.” In contrast, the previous generation—the millennials, sometimes called the “me generation”—got its start in an era of economic prosperity and focuses on the self. Its members are more idealistic, more confrontational, and less willing to accept diverse points of view.
Such behaviors influence the way Gen Zers view consumption and their relationships with brands. Companies should be attuned to three implications for this generation: consumption as access rather than possession, consumption as an expression of individual identity, and consumption as a matter of ethical concern. Coupled with technological advances, this generational shift is transforming the consumer landscape in a way that cuts across all socioeconomic brackets and extends beyond Gen Z, permeating the whole demographic pyramid. The possibilities now emerging for companies are as transformational as they are challenging. Businesses must rethink how they deliver value to the consumer, rebalance scale and mass production against personalization, and—more than ever—practice what they preach when they address marketing issues and work ethics.
Meet True Gen
Generations are shaped by the context in which they emerged (Exhibit 1). Baby boomers, born from 1940 to 1959, were immersed in the post–World War II context and are best represented by consumption as an expression of ideology. Gen Xers (born 1960–79) consumed status, while millennials (born 1980–94) consumed experiences. For Generation Z, as we have seen, the main spur to consumption is the search for truth, in both a personal and a communal form (Exhibit 2). This generation feels comfortable not having only one way to be itself. Its search for authenticity generates greater freedom of expression and greater openness to understanding different kinds of people.
Exhibit 1
We strive to provide individuals with disabilities equal access to our website. If you would like information about this content we will be happy to work with you. Please email us at: McKinsey_Website_Accessibility@mckinsey.com
Exhibit 2
We strive to provide individuals with disabilities equal access to our website. If you would like information about this content we will be happy to work with you. Please email us at: McKinsey_Website_Accessibility@mckinsey.com
‘Undefined ID’: Expressing individual truth
I need to be free; I need to be myself, increasingly be myself, every day. With the internet, I feel much more free.
—Female respondent, 22, city of São Paulo
I really like things that are unisex! I think it’s absurd that stores and brands split everything into “male” and “female.” After all, fabric is genderless.
—Female respondent, 22, Goiânia
For Gen Zers, the key point is not to define themselves through only one stereotype but rather for individuals to experiment with different ways of being themselves and to shape their individual identities over time (Exhibit 3). In this respect, you might call them “identity nomads.”
Exhibit 3
We strive to provide individuals with disabilities equal access to our website. If you would like information about this content we will be happy to work with you. Please email us at: McKinsey_Website_Accessibility@mckinsey.com
Seventy-six percent of Gen Zers say they are religious. At the same time, they are also the generation most open to a variety of themes not necessarily aligned with the broader beliefs of their declared religions. For example, 20 percent of them do not consider themselves exclusively heterosexual, as opposed to 10 percent for other generations. Sixty percent of Gen Zers think that same-sex couples should be able to adopt children—ten percentage points more than people in other generations do.
Gender fluidity may be the most telling reflection of “undefined ID,” but it isn’t the only one. Gen Zers are always connected. They constantly evaluate unprecedented amounts of information and influences. For them, the self is a place to experiment, test, and change. Seven out of ten Gen Zers say it is important to defend causes related to identity, so they are more interested than previous generations have been in human rights; in matters related to race and ethnicity; in lesbian, gay, bisexual, and transgender issues; and in feminism (Exhibit 4).
Exhibit 4
We strive to provide individuals with disabilities equal access to our website. If you would like information about this content we will be happy to work with you. Please email us at: McKinsey_Website_Accessibility@mckinsey.com
‘Communaholic’: Connecting to different truths
We each have our own style and way of being, but what binds us is that we accept and understand everyone’s styles.
—Male respondent, 16, Recife
Gen Zers are radically inclusive. They don’t distinguish between friends they meet online and friends in the physical world. They continually flow between communities that promote their causes by exploiting the high level of mobilization technology makes possible. Gen Zers value online communities because they allow people of different economic circumstances to connect and mobilize around causes and interests. (Sixty-six percent of the Gen Zers in our survey believe that communities are created by causes and interests, not by economic backgrounds or educational levels. That percentage is well above the corresponding one for millennials, Gen Xers, and baby boomers.) Fifty-two percent of Gen Zers think it is natural for every individual to belong to different groups (compared with 45 percent of the people in other generations), and Gen Zers have no problem with moving between groups.
‘Dialoguer’: Understanding different truths
We must practice tolerance, and we must learn to listen and accept differences.
—Male respondent, 20, Gioânia
Exhibit 5
We strive to provide individuals with disabilities equal access to our website. If you would like information about this content we will be happy to work with you. Please email us at: McKinsey_Website_Accessibility@mckinsey.com
Gen Zers believe in the importance of dialogue and accept differences of opinion with the institutions in which they participate and with their own families (Exhibit 5). They can interact with institutions that reject their personal values without abandoning those values. The fact that Gen Zers feel comfortable interacting with traditional religious institutions without abandoning personal beliefs that might not be broadly accepted by these institutions also demonstrates their pragmatism. Rather than spurn an institution altogether, Gen Zers would rather engage with it to extract whatever makes sense for them.
Members of this generation therefore tend to believe that change must come from dialogue: 57 percent of millennials, Gen Xers, and baby boomers think they would have to break with the system to change the world, compared with 49 percent of Gen Zers. Gen Z is also more willing to accommodate the failings of companies. Thirty-nine percent of the people in this generation, for example, expect companies to answer customer complaints in the same day; for the three earlier generations, the percentage is much higher—52 percent.
Gen Z’s belief in dialogue combines a high value for individual identity, the rejection of stereotypes, and a considerable degree of pragmatism. That brings us to the fourth core behavior of Gen Z.
‘Realistic’: Unveiling the truth behind all things
I don’t believe this talk of investing in the dream and all that. Work is work.
—Female respondent, 22, Salvador, state of Bahia
Gen Zers, with vast amounts of information at their disposal, are more pragmatic and analytical about their decisions than members of previous generations were. Sixty-five percent of the Gen Zers in our survey said that they particularly value knowing what is going on around them and being in control. This generation of self-learners is also more comfortable absorbing knowledge online than in traditional institutions of learning.
What’s more, Gen Z was raised at a time of global economic stress—in fact, the greatest economic downturn in Brazil’s history. These challenges made Gen Zers less idealistic than the millennials we surveyed (Exhibit 6). Many Gen Zers are keenly aware of the need to save for the future and see job stability as more important than a high salary. They already show a high preference for regular employment rather than freelance or part-time work, which may come as a surprise compared to the attitude of millennials, for example. According to the survey, 42 percent of Gen Zers from 17 to 23 years old are already gainfully employed in either full- or part-time jobs or as freelance workers—a high percentage for people so young.
Exhibit 6
We strive to provide individuals with disabilities equal access to our website. If you would like information about this content we will be happy to work with you. Please email us at: McKinsey_Website_Accessibility@mckinsey.com
Gen Z: Consumption and implications for companies
The youthful forms of behavior we discuss here are influencing all generations and, ultimately, attitudes toward consumption as well. Three forces are emerging in a powerful confluence of technology and behavior.
Consumption re-signified: From possession to access
This more pragmatic and realistic generation of consumers expects to access and evaluate a broad range of information before purchases. Gen Zers analyze not only what they buy but also the very act of consuming. Consumption has also gained a new meaning. For Gen Z—and increasingly for older generations as well—consumption means having access to products or services, not necessarily owning them. As access becomes the new form of consumption, unlimited access to goods and services (such as car-riding services, video streaming, and subscriptions) creates value. Products become services, and services connect consumers.
As collaborative consumption gains traction, people are also starting to view it as a way to generate additional income in the “gig economy.” Another aspect of the gig economy involves consumers who take advantage of their existing relationships with companies to generate additional income by working temporarily for them. Some companies are already embracing the implications.
Car manufacturers, for example, are renting out vehicles directly to consumers, so that instead of selling 1,000 cars, these companies may sell one car 1,000 times. The role of sporting-goods businesses, likewise, has shifted to helping people become better athletes by providing access to equipment, technology, coaching, and communities of like-minded consumers. Similarly, traditional consumer-goods companies should consider creating platforms of products, services, and experiences that aggregate or connect customers around brands. Companies historically defined by the products they sell or consume can now rethink their value-creation models, leveraging more direct relationships with consumers and new distribution channels.
Singularity: Consumption as an expression of individual identity
The core of Gen Z is the idea of manifesting individual identity. Consumption therefore becomes a means of self-expression—as opposed, for example, to buying or wearing brands to fit in with the norms of groups. Led by Gen Z and millennials, consumers across generations are not only eager for more personalized products but also willing to pay a premium for products that highlight their individuality. Fifty-eight percent of A-class and 43 percent of C-class consumers2 say they are willing to pay more for personalized offerings. Seventy percent of A-class and 58 percent of C-class consumers are willing to pay a premium for products from brands that embrace causes those consumers identify with. And here’s another finding that stood out in our survey: 48 percent of Gen Zers—but only 38 percent of consumers in other generations—said they value brands that don’t classify items as male or female. For most brands, that is truly new territory.
Although expectations of personalization are high, consumers across generations are not yet totally comfortable about sharing their personal data with companies. Only 10 to 15 percent of them declare not to have any issues in sharing personal data with companies. If there is a clear counterpart from companies to consumers, then the number of consumers willing to share personal information with companies goes up to 35 percent—still a relatively small number.
As the on- and offline worlds converge, consumers expect more than ever to consume products and services any time and any place, so omnichannel marketing and sales must reach a new level. For consumers who are always and everywhere online, the online–offline boundary doesn’t exist. Meanwhile, we are entering the “segmentation of one” age now that companies can use advanced analytics to improve their insights from consumer data. Customer information that companies have long buried in data repositories now has strategic value, and in some cases information itself creates the value. Leading companies should therefore have a data strategy that will prepare them to develop business insights by collecting and interpreting information about individual consumers while protecting data privacy.
For decades, consumer companies and retailers have realized gains through economies of scale. Now they may have to accept a two-track model: the first for scale and mass consumption, the other for customization catering to specific groups of consumers or to the most loyal consumers. In this scenario, not only marketing but also the supply chain and manufacturing processes would require more agility and flexibility. For businesses, that kind of future raises many questions. How long will clothing collections grouped by gender continue to make sense, for example? How should companies market cars or jewelry in an inclusive, unbiased way? To what extent should the need for a two-speed business transform the internal processes and structure of companies?
Consumption anchored on ethics
Finally, consumers increasingly expect brands to “take a stand.” The point is not to have a politically correct position on a broad range of topics. It is to choose the specific topics (or causes) that make sense for a brand and its consumers and to have something clear to say about those particular issues. In a transparent world, younger consumers don’t distinguish between the ethics of a brand, the company that owns it, and its network of partners and suppliers. A company’s actions must match its ideals, and those ideals must permeate the entire stakeholder system.
Gen Z consumers are mostly well educated about brands and the realities behind them. When they are not, they know how to access information and develop a point of view quickly. If a brand advertises diversity but lacks diversity within its own ranks, for example, that contradiction will be noticed. In fact, members of the other generations we surveyed share this mind-set. Seventy percent of our respondents say they try to purchase products from companies they consider ethical. Eighty percent say they remember at least one scandal or controversy involving a company. About 65 percent try to learn the origins of anything they buy—where it is made, what it is made from, and how it is made. About 80 percent refuse to buy goods from companies involved in scandals.
All this is relevant for businesses, since 63 percent of the consumers we surveyed said that recommendations from friends are their most trusted source for learning about products and brands. The good news is that consumers—in particular Gen Zers—are tolerant of brands when they make mistakes, if the mistakes are corrected. That path is more challenging for large corporations, since a majority of our respondents believe that major brands are less ethical than small ones.
For consumers, marketing and work ethics are converging. Companies must therefore not only identify clearly the topics on which they will take positions but also ensure that everyone throughout the value chain gets on board. For the same reason, companies ought to think carefully about the marketing agents who represent their brands and products. Remember too that consumers increasingly understand that some companies subsidize their influencers. Perhaps partly for that reason, consumers tend to pay more attention to closer connections—for example, Instagram personas with 5,000 to 20,000 followers. Marketing in the digital age is posing increasingly complex challenges as channels become more fragmented and ever changing.
Young people have always embodied the zeitgeist of their societies, profoundly influencing trends and behavior alike. The influence of Gen Z—the first generation of true digital natives—is now radiating outward, with the search for truth at the center of its characteristic behavior and consumption patterns. Technology has given young people an unprecedented degree of connectivity among themselves and with the rest of the population. That makes generational shifts more important and speeds up technological trends as well. For companies, this shift will bring both challenges and equally attractive opportunities. And remember: the first step in capturing any opportunity is being open to it.